
Occupancy Update – September 2026

With the PBSA leasing cycle drawing to a close, September marks the final critical window for securing bookings ahead of the new academic year. This update examines how the market performed through the end of the month, analysing late-stage booking velocity, year-on-year occupancy trends, and seasonal demand patterns across bed types.
The Occupancy Survey continues to provide the most comprehensive view of UK PBSA leasing activity available, now capturing more than half of the private PBSA direct-let market and offering valuable insight into current dynamics across all major student accommodation markets.
StuRents Occupancy Survey includes private PBSA direct-let bookings only. University halls and private beds on nomination agreements are excluded.
Source: StuRents Occupancy Survey
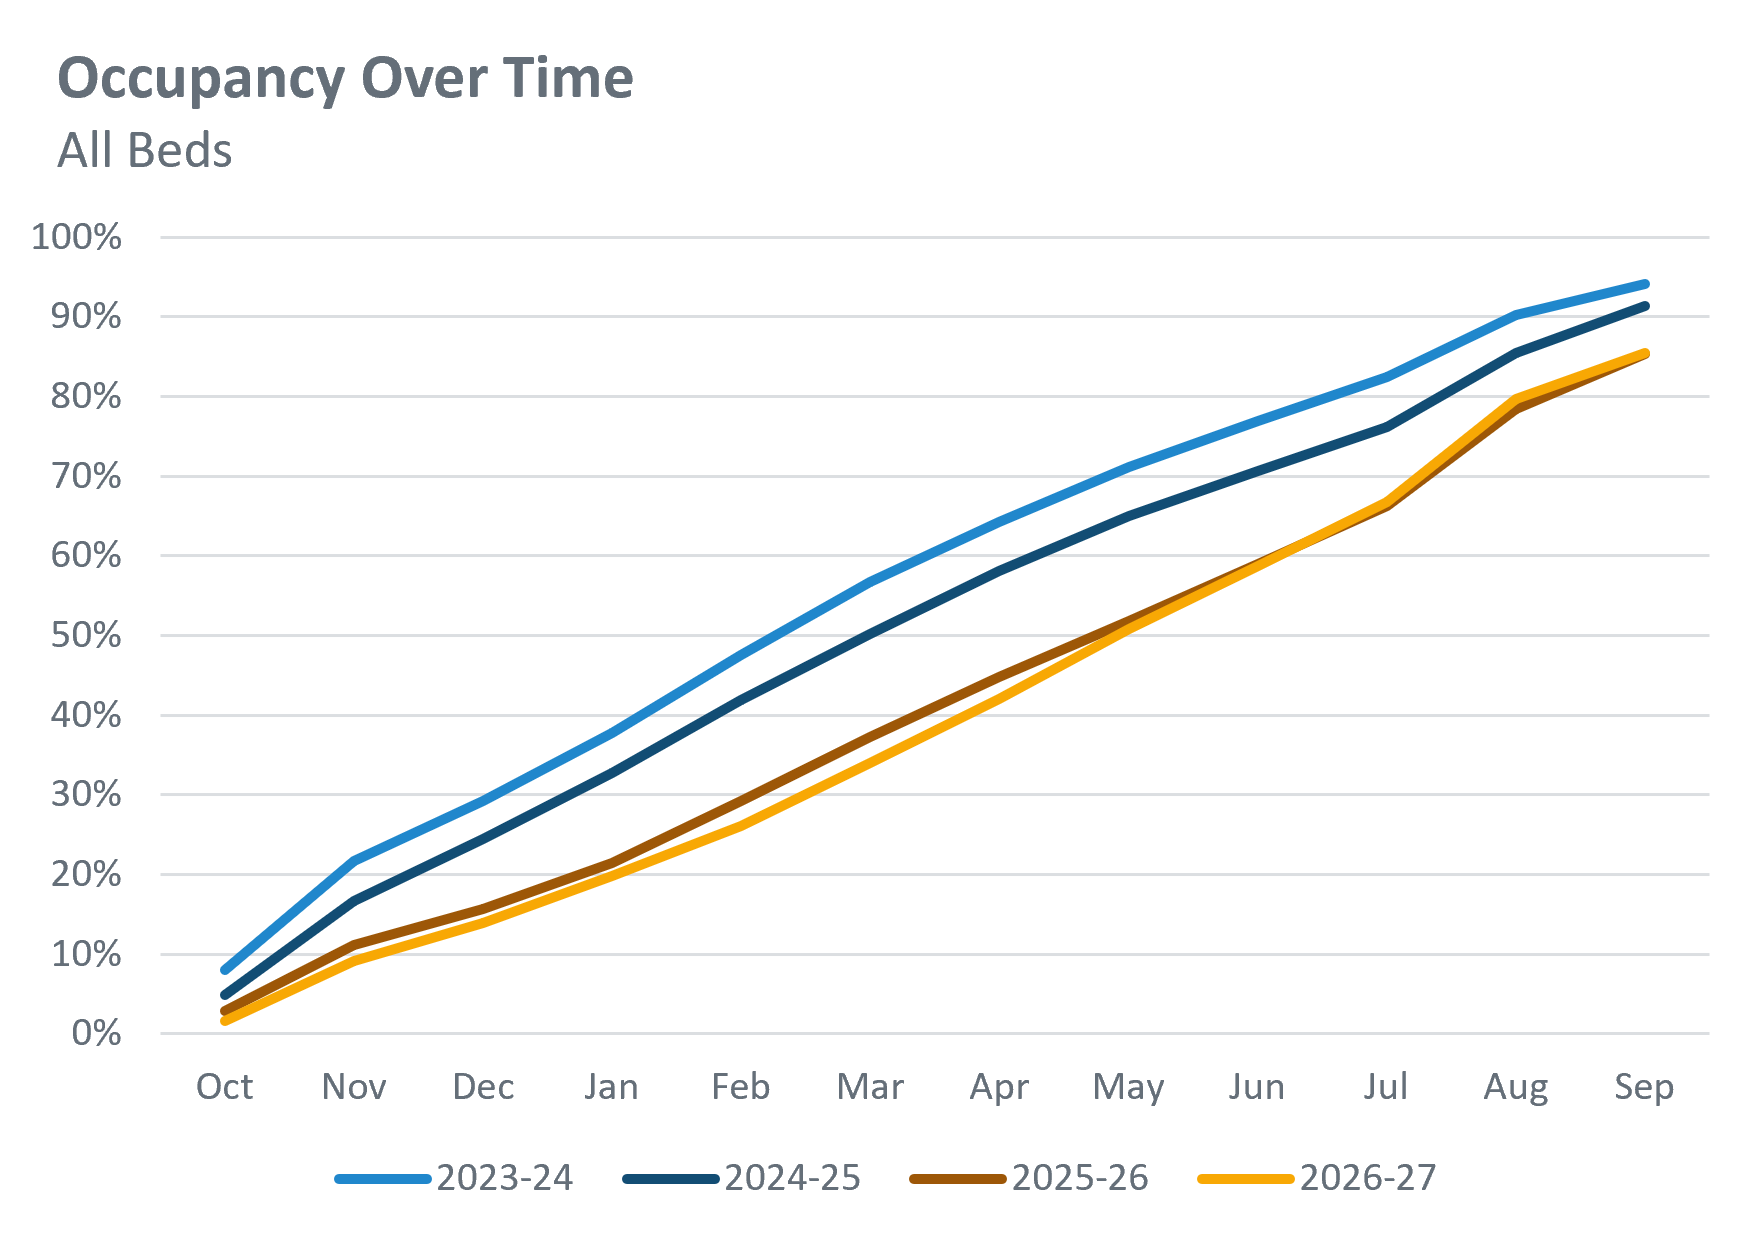
The 26-27 cycle has tracked closely with that of 25-26 throughout the year, and has finished flat in line with it as of the end of September. Across all bed types in all 29 locations we cover, average occupancy for 26-27 stood at 85.3%, which represents no difference year-on-year (YoY).
Source: StuRents Occupancy Survey
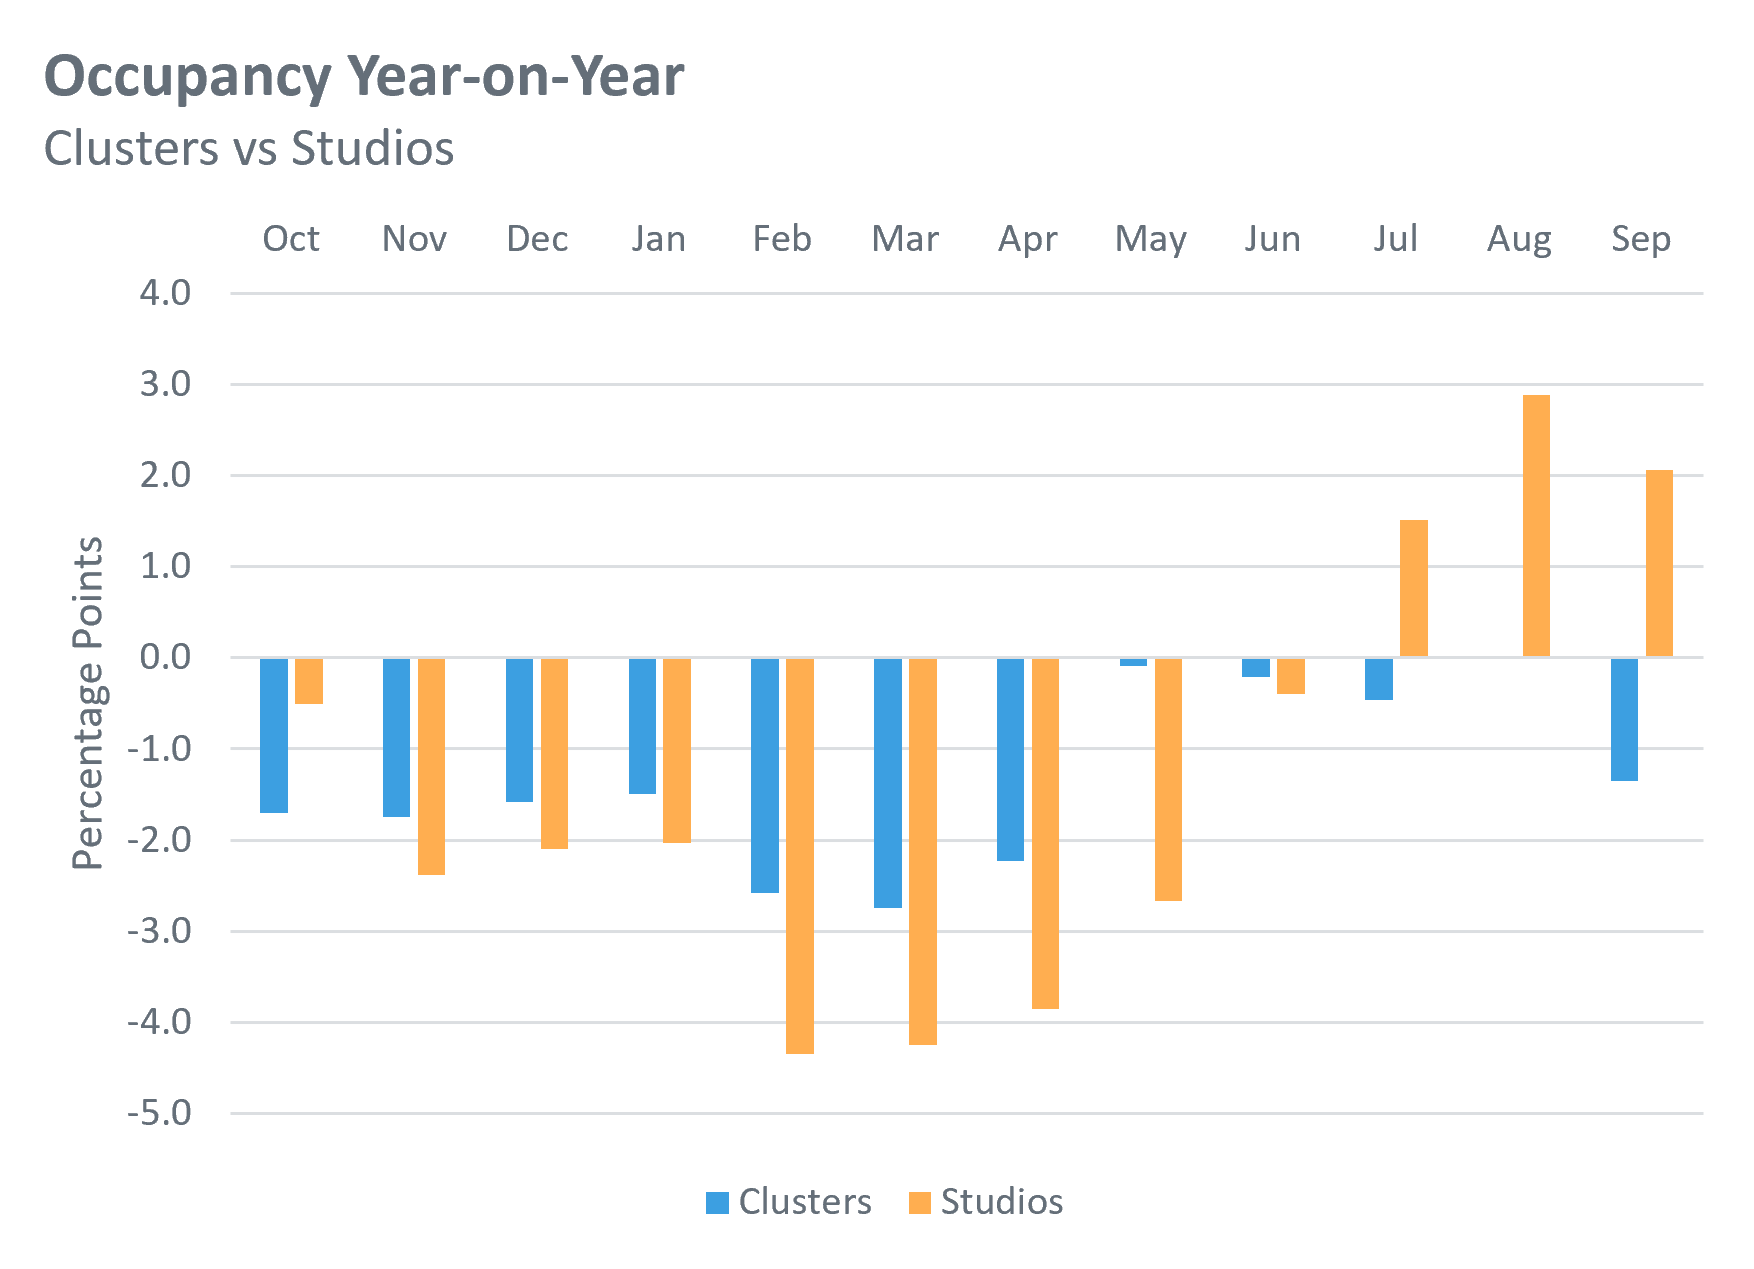
This chart shows how the YoY gap in occupancy has changed throughout the cycle for both cluster beds and studios. While the clusters gap briefly turned positive in August, it fell back into negative territory at the close of the cycle, finishing September 1.4 percentage points behind last year. The studios gap, however, maintained its strong summer recovery; after flipping positive in July, it ended the cycle in September comfortably ahead of the previous year with a 2.1 percentage point lead.
Source: StuRents Occupancy Survey
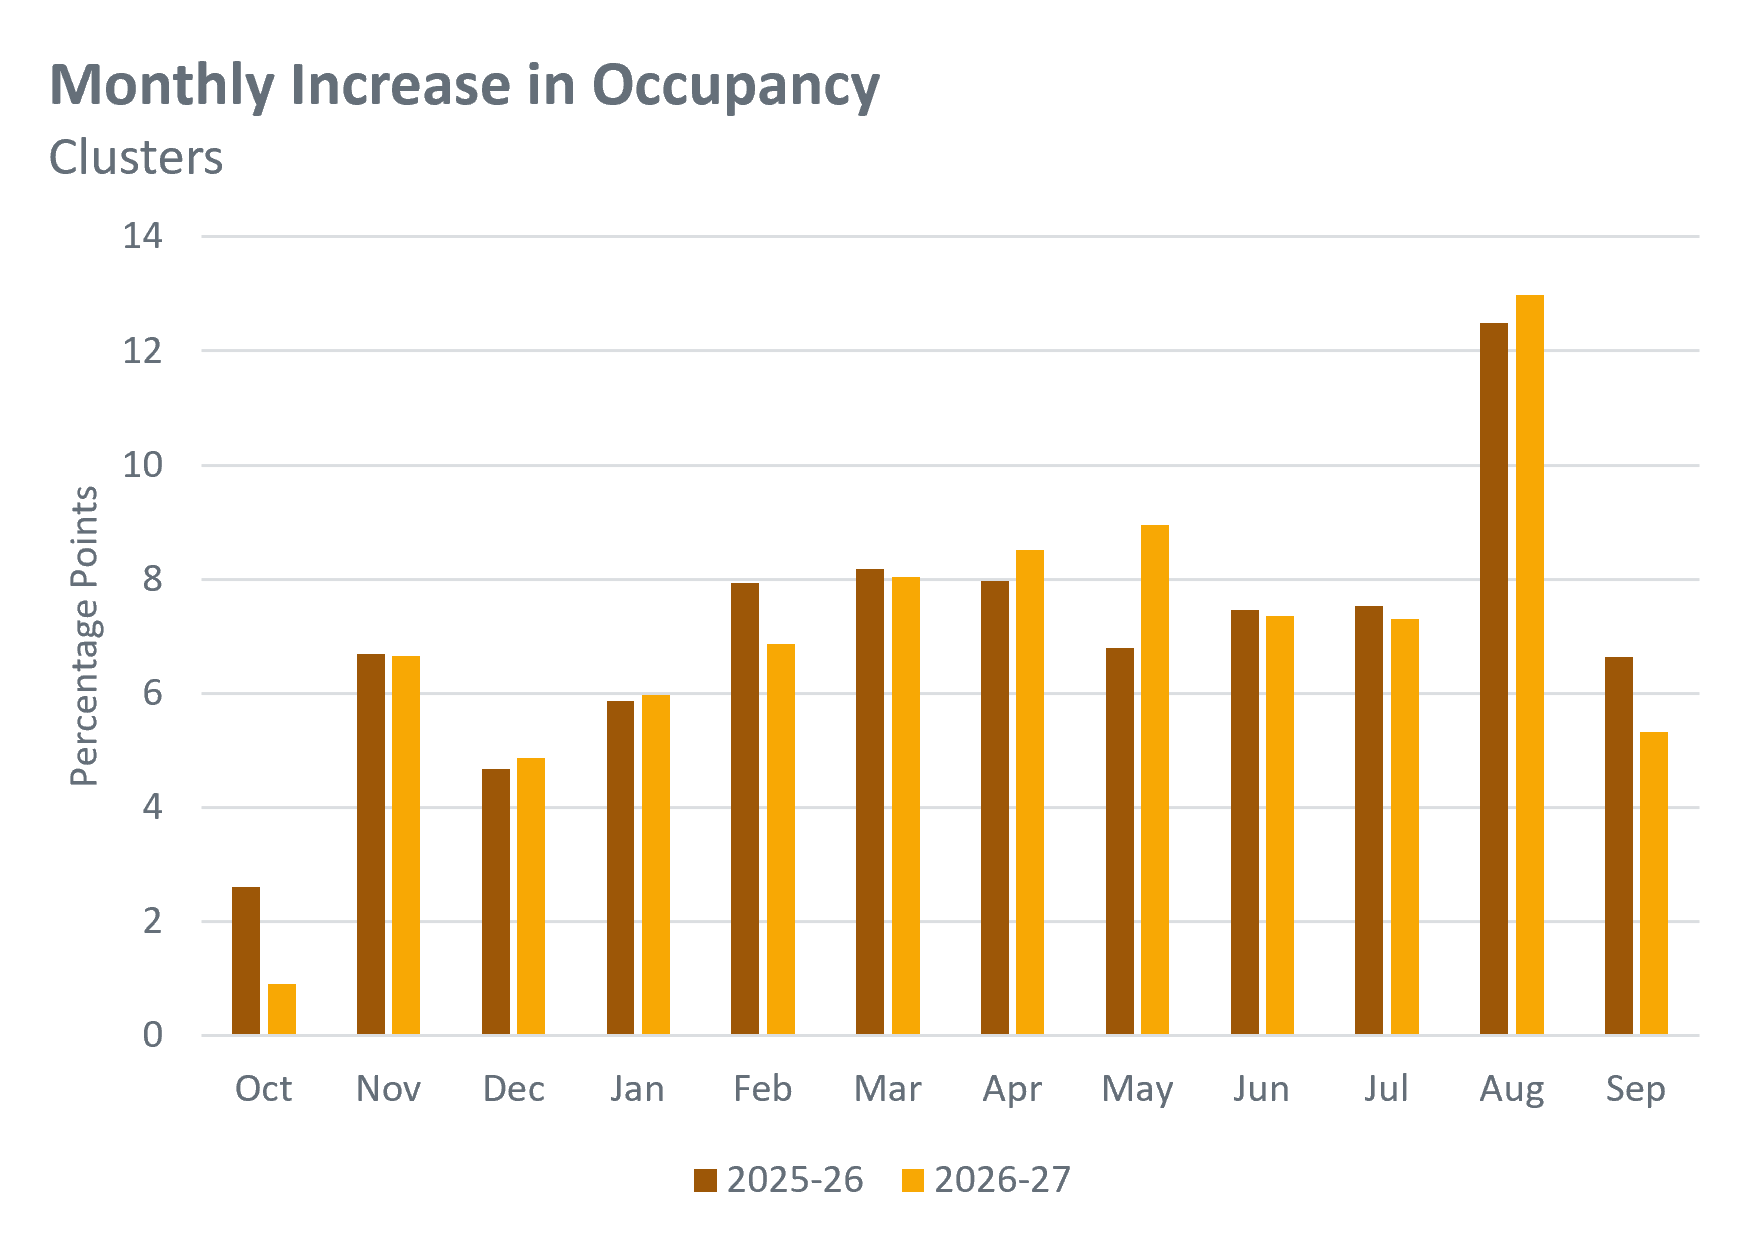
Following the late-summer surge in August, cluster occupancy growth tapered off in September as the cycle came to a close. The final month delivered a 5.3 percentage point increase, falling short of the 6.6-point gain recorded at the end of the 2025-26 cycle. As a result, final cluster occupancy ended September at 83.5%, slipping back behind last year's finish by 1.4 points.
Source: StuRents Occupancy Survey
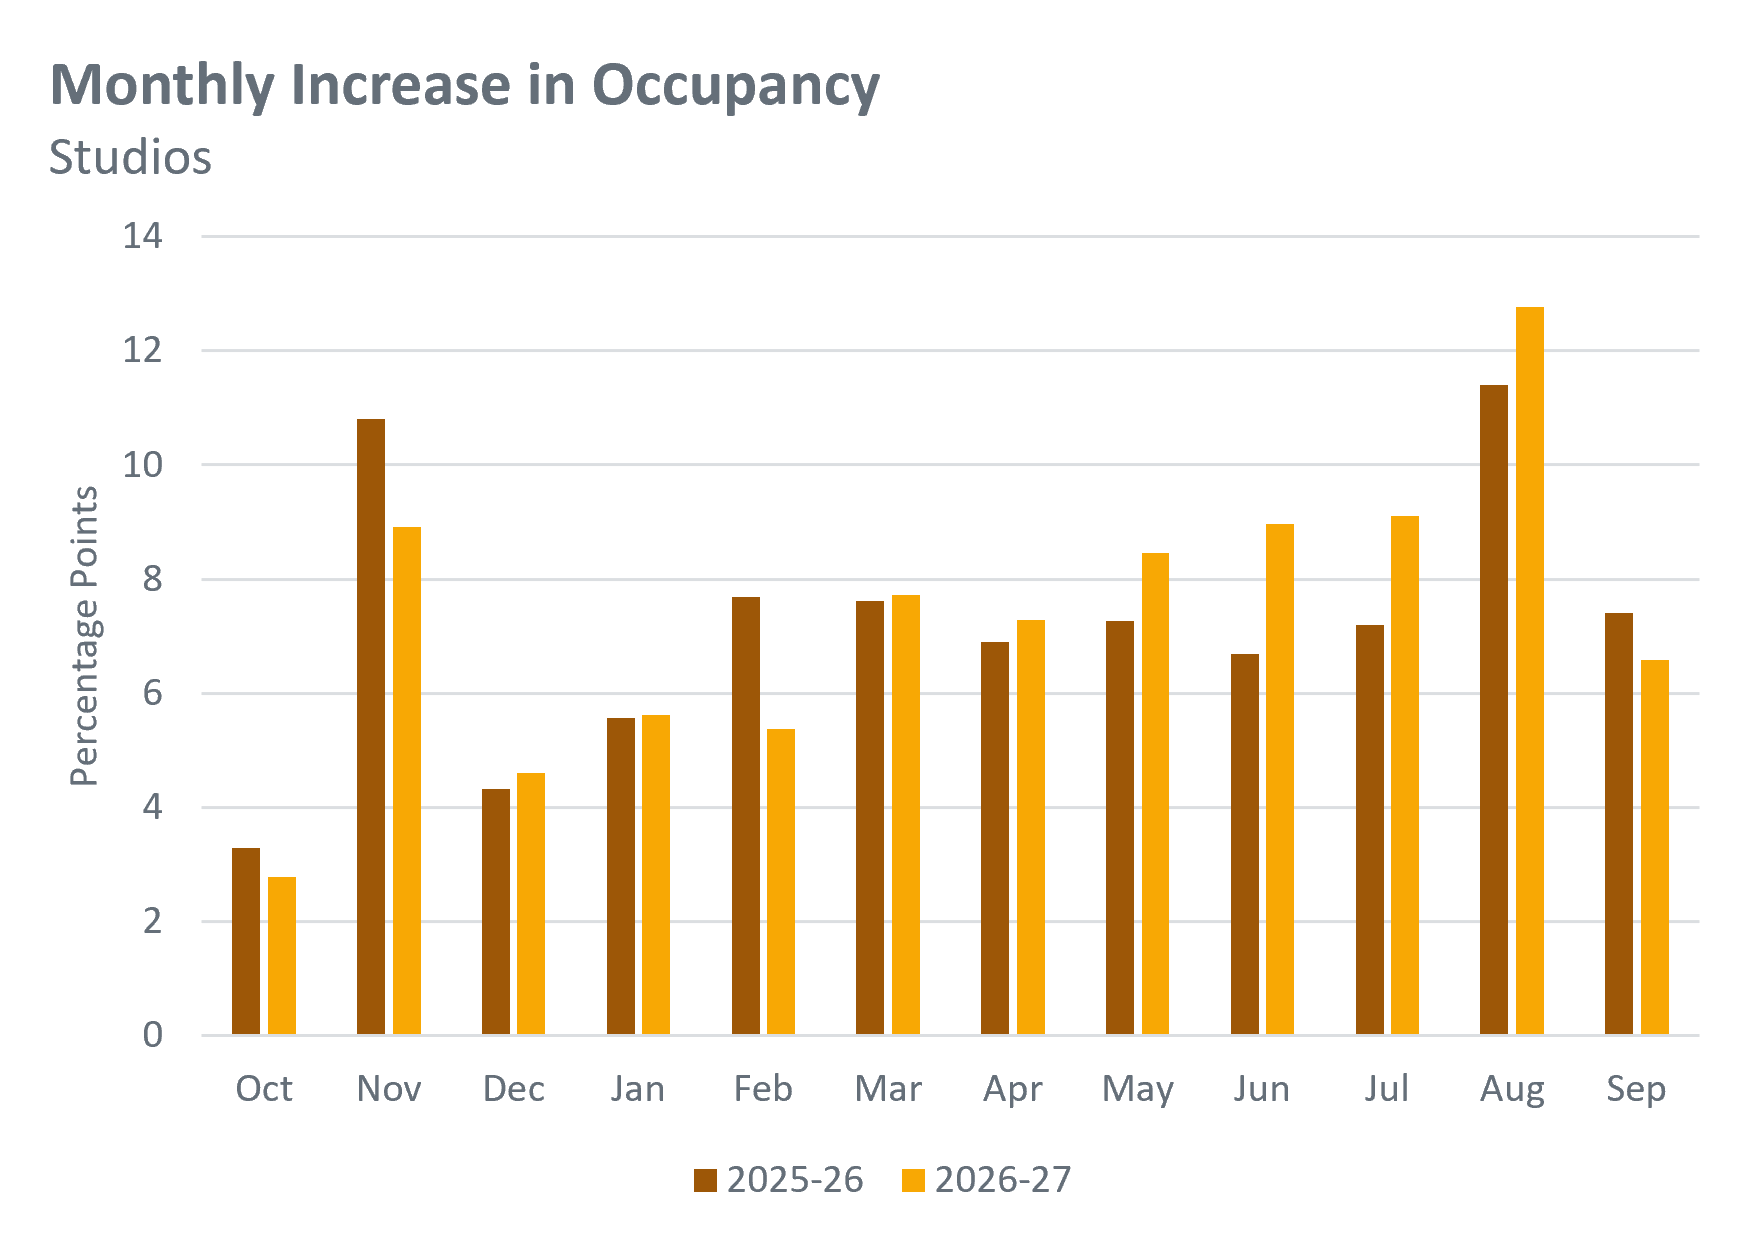
For studios, September closed the cycle with a 6.6 percentage point month-on-month increase. While this final push was slightly softer than the 7.4 points added during the same period last year, total studio occupancy finished strong at 88.2%, maintaining a solid 2.1 percentage point lead over the 2025-26 cycle.
Source: StuRents Occupancy Survey
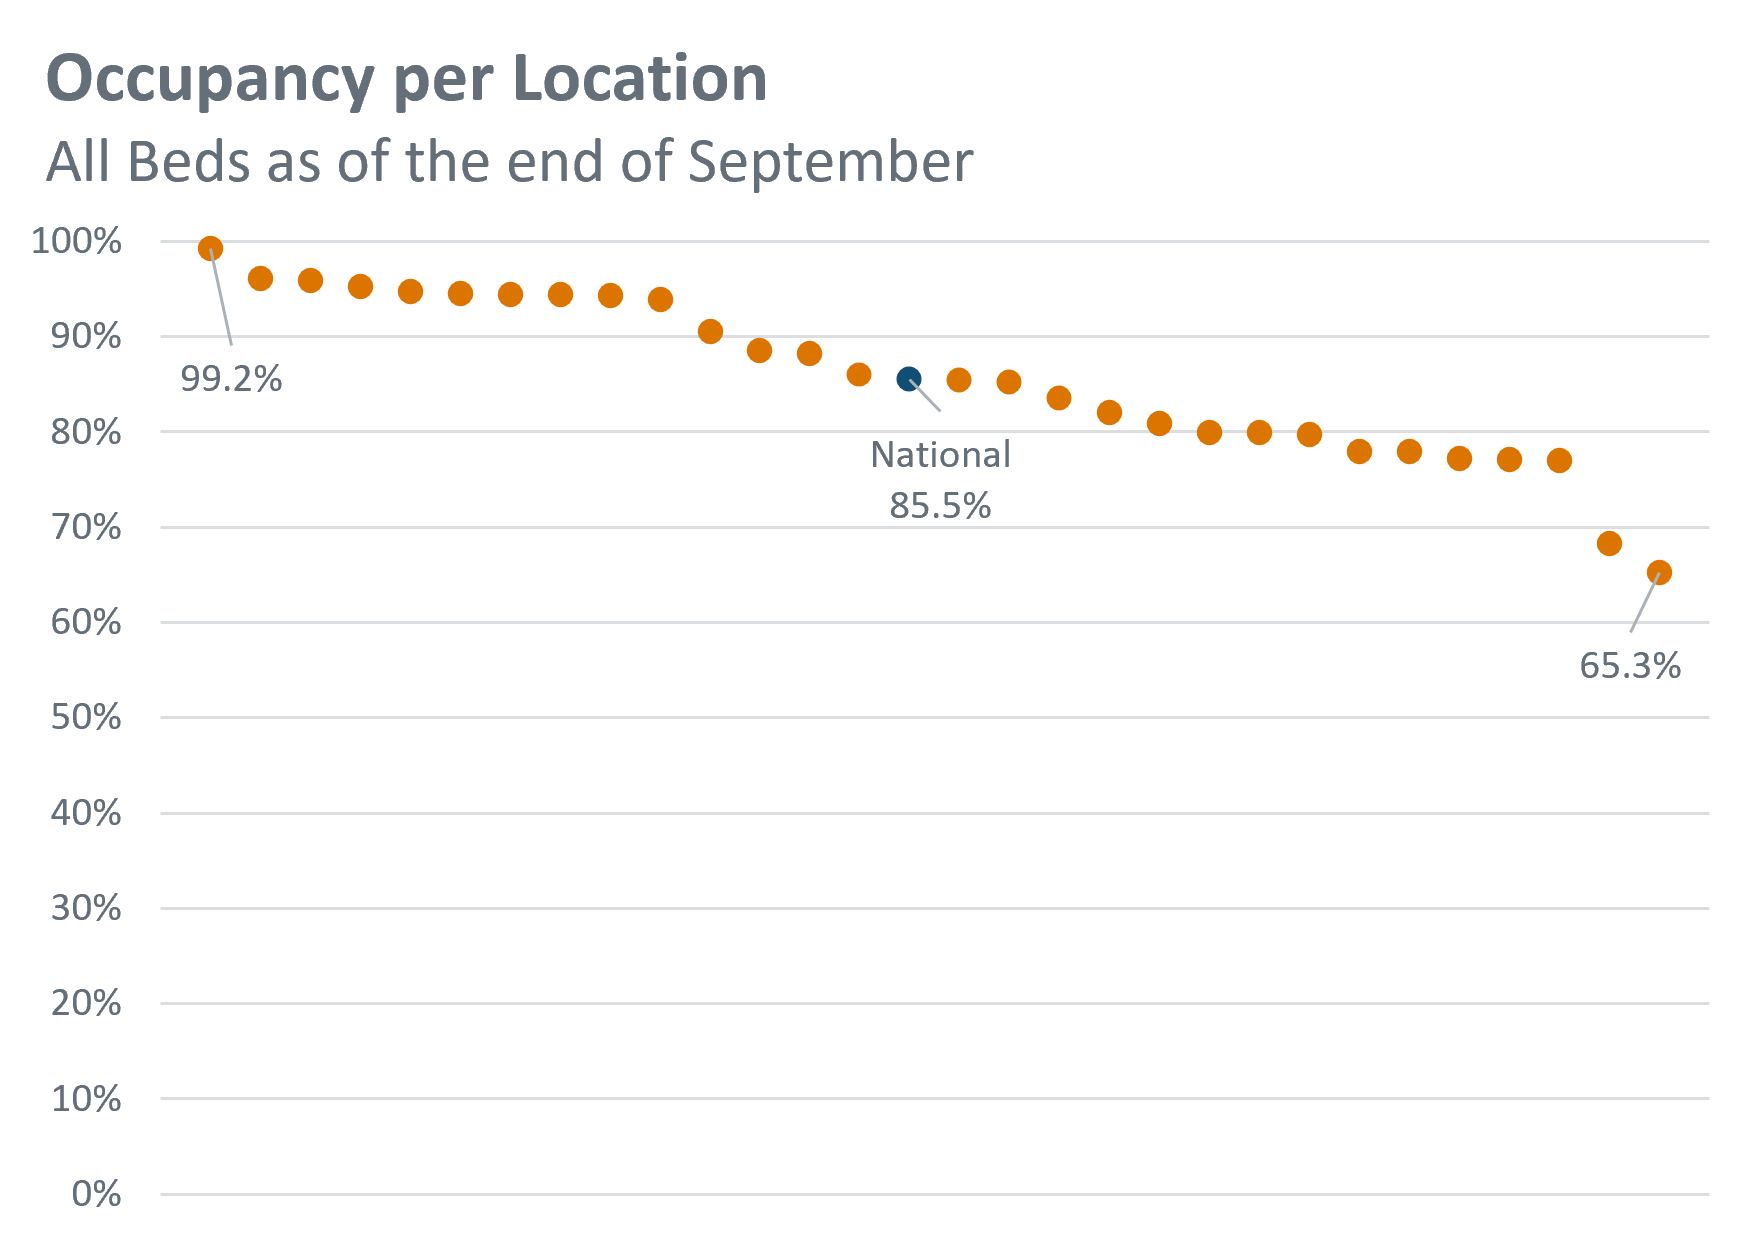
The chart above compares end-of-September occupancy across the 29 survey locations, alongside the national average. Performance varied considerably, with occupancy levels ranging from 99.2% in the highest-performing location to 65.3% in the lowest. These wide disparities reflect the differing supply and demand conditions that exist across local accommodation markets in the UK.
In summary, the 2026-27 PBSA leasing cycle has concluded in a way that shows that overall market conditions are similar to that of last year. National occupancy reached 85.3% by the end of September, marking a zero percentage point difference year-on-year, albeit with a strong late-season recovery in studio demand. However, the 34.0 percentage point disparity between the highest and lowest performing locations underlines that the UK market remains highly fragmented, with asset performance heavily dependent on localised supply and demand fundamentals.
For more information about our proprietary, highly granular data covering UK student accommodation, contact the StuRents Research team today. Book a demo of our Data Portal to find out how you can have up-to-the-minute university housing insights at your fingertips, or get in touch with us about our Occupancy Survey.
Share

Article by
Research Analyst at StuRents
Sam Gillespie is a research analyst in StuRents’ research division, StuRents Intelligence.
